Categories
Mortgage MinutePublished September 14, 2026
Mortgage Rate Update: Napa & Northern California – Week of September 14, 2026
Mortgage Rates Crossed 7%. Buyers Still Have Options.
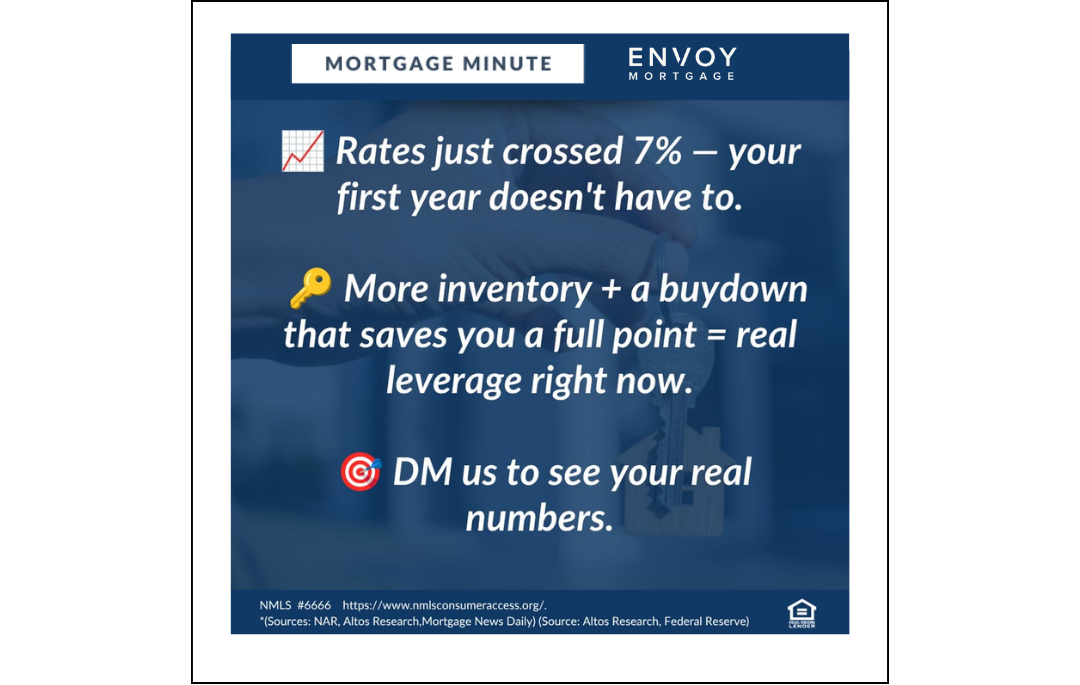
Mortgage rates moved above 7% last week, giving buyers another reason to pay close attention to affordability. Mortgage News Daily's daily index ended September 11 at 7.12% for a top-tier 30-year fixed mortgage, its highest reading in more than a year. Other mortgage surveys showed somewhat lower averages because their methodologies and reporting periods differ.
There is no getting around the fact that higher rates affect buying power and monthly payments. But the rate is only one part of what has changed in the housing market.
Inventory has grown while demand remains relatively subdued. Redfin reported that August brought the highest level of new listings in more than four years, while the total number of homes for sale reached its highest level since 2020. Nearly three in five homes sold below their original asking price nationally.
For buyers who can comfortably afford a purchase, that combination creates an interesting tradeoff. Financing is more expensive, but buyers may have more homes to choose from and, depending on the property, more opportunity to negotiate than they did when rates were lower and competition was stronger.
Why Mortgage Rates Moved Above 7%
Mortgage rates had already been moving higher before crossing the 7% threshold. On September 10, Mortgage News Daily reported its average top-tier 30-year fixed rate jumped from 6.97% to 7.07% in one day, following another increase the previous day. It attributed most of that move to renewed inflation concerns, including rising fuel prices and a Producer Price Index report that was poorly received by bond markets.
It's also worth understanding why you may see different mortgage rates reported in different places. Mortgage News Daily's daily index incorporates the impact of points, while Freddie Mac publishes a weekly survey with a different methodology. As of September 11, Mortgage News Daily showed 7.12%, while Freddie Mac's September 10 weekly reading was 6.76% and the Mortgage Bankers Association's September 9 reading was 6.85%.
Those aren't contradictions. They're different measures of a market that can move quickly.
For an individual buyer, the rate available will also depend on credit, loan type, down payment, points, property type and other factors. A national average is useful for understanding direction, but it isn't a personalized quote.
The Housing Market Is Giving Buyers Something Rates Aren't
While borrowing costs have moved higher, the housing market itself has become more favorable to many buyers.
Redfin's September 10 market update found that the typical monthly mortgage payment nationally had reached a 14-month high. At the same time, pending sales remained near their lowest level since February, active listings were up from a year earlier, and about 21% of listings had experienced a price reduction.
That doesn't mean every seller is ready to make a deal. Northern California varies considerably by location and price point. In fact, Redfin classified San Francisco as one of only five major U.S. metros that remained a seller's market in August.
But for many buyers, having more homes available creates breathing room that was missing during the most competitive markets of recent years. Instead of making a decision under immediate pressure, buyers may be able to compare properties, watch pricing and understand which sellers have room to negotiate.
Depending on the individual home, that conversation might include purchase price, closing costs, repairs, closing timeline or other allowable seller concessions.
A 7% Headline Doesn't Necessarily Tell You Your First-Year Payment
This week's financing spotlight is particularly timely because it addresses the psychological hurdle of seeing a mortgage rate beginning with a seven.
Envoy Mortgage's RateSaver is described in the information provided for this week's update as a lender-paid 1/0 temporary buydown for qualified buyers. Under the program, the buyer's effective payment rate during the first year is reduced by one percentage point, with the lender funding the buydown rather than the buyer.
So, as a simplified example, if an eligible buyer's note rate were 7.125%, the first-year payment under a 1/0 buydown would generally be calculated using an effective rate of 6.125%. After the temporary period ends, payments would be based on the full note rate according to the program terms.
That distinction matters. The permanent mortgage rate isn't being changed. The program temporarily reduces the payment during the first year.
Eligibility, loan terms, qualifying requirements and availability should be confirmed directly with Envoy Mortgage before a buyer relies on the program. Buyers also need to be comfortable with the full payment that applies after the temporary buydown expires.
Higher Rates and More Inventory Create a Different Kind of Opportunity
A few years ago, a buyer might have benefited from a substantially lower mortgage rate but faced a completely different purchasing environment: fewer homes, multiple offers and considerably less ability to negotiate.
Today's buyer faces almost the reverse.
Financing costs are higher, but supply has improved. Nationally, sellers outnumbered buyers by 58% in August, the largest gap in Redfin's records.
That doesn't make higher rates insignificant. Instead, it means buyers should evaluate the complete transaction.
A seller concession worth thousands of dollars, a negotiated repair, a price adjustment or an eligible financing program can change the numbers. None of those automatically makes buying the right decision, but neither does a 7% headline automatically make waiting the right decision.
This is where having both your agent and lender involved early becomes especially useful. Your agent can evaluate the property, comparable sales, competing inventory and seller position. Your lender can show you what various financing structures actually do to the payment and cash required at closing.
What This Means in Napa and Northern California
National statistics provide context, but EO&A's buyers aren't purchasing the national housing market. They're buying individual homes throughout Napa, Sonoma, Marin, Solano, Contra Costa and San Francisco.
The negotiating environment can look completely different from one property to another. A desirable Napa home that is priced correctly may attract attention quickly. A Sonoma County property that has been available for several weeks may give a buyer more room to discuss terms. Solano or Contra Costa buyers may encounter a different inventory picture altogether, while certain Marin and San Francisco properties can remain highly competitive.
That's why the 7% rate headline shouldn't become the entire home-buying strategy.
For someone who isn't financially ready, higher rates may absolutely be a reason to wait. But a qualified buyer who has been sitting on the sidelines solely because rates crossed a particular threshold may want to look at the homes and negotiating conditions available before making that decision.
The Numbers Matter More Than the Headline
This isn't about convincing buyers to ignore mortgage rates. Quite the opposite.
It's about looking at all the numbers.
The purchase price matters. The mortgage rate matters. The monthly payment matters. Cash required at closing matters. Seller concessions matter. The amount of competition for the home matters. And, for an eligible buyer considering a temporary buydown, the payment after that initial period matters just as much as the first-year payment.
Today's market gives buyers an opportunity to evaluate those pieces together.
If you're considering buying in Northern California, EO&A can help you understand current inventory, recent comparable sales and what may be negotiable on the homes you're considering. A qualified lender can then show you your actual payment options and determine whether a program such as RateSaver fits your situation.
A rate above 7% deserves your attention.
It doesn't have to make the entire decision for you.
Happy house hunting 🏡
Sources: Mortgage News Daily; Redfin Housing Market Updates; financing information supplied by Envoy Mortgage.
Common Questions About This Week's Mortgage Update
Are mortgage rates above 7% right now?
Mortgage News Daily's daily index showed the average top-tier 30-year fixed mortgage at 7.12% on September 11, 2026. Other widely followed mortgage surveys were somewhat lower because they use different methodologies and reporting periods. The actual rate offered to an individual borrower depends on factors including credit, down payment, loan type, points and property characteristics, so national averages should be treated as market benchmarks rather than personalized quotes.
What is a 1/0 mortgage rate buydown?
A 1/0 buydown temporarily reduces the effective rate used to calculate a borrower's payment by one percentage point during the first year. After that temporary period, the payment is based on the full note rate according to the loan terms. A buydown does not permanently reduce the mortgage's note rate, so buyers should make sure they understand and can afford the full payment that applies after the temporary reduction ends.
What is Envoy Mortgage's RateSaver program?
Based on the information provided for this week's Mortgage Minute, RateSaver is a lender-paid 1/0 temporary buydown available to qualified buyers through Envoy Mortgage. The lender funds the temporary reduction rather than the buyer. Eligibility, loan programs, terms and availability can vary, so buyers should speak directly with Envoy Mortgage to determine whether RateSaver is available for their transaction and review the full financing terms.
Does higher housing inventory give buyers more negotiating room?
It can. Nationally, Redfin reported that housing supply reached a six-year high in August and nearly three in five homes sold below their original asking price. More available homes can give buyers alternatives and put additional pressure on some sellers to negotiate. However, Northern California conditions vary significantly by city, neighborhood and property, so negotiating potential should always be evaluated at the individual-home level.
Should I wait for mortgage rates to fall before buying?
That depends on your finances and the opportunities available in your local market. Lower future rates could improve monthly affordability, but market conditions may also change while you wait. Inventory, home prices, competition and seller concessions can all move independently of mortgage rates. Comparing today's actual purchase options with your budget is generally more useful than making the decision around a prediction of where rates may go.
Search Homes • Explore Financing Resources • Meet the EO&A Team
Contact EO&A today to schedule your free home value review.
Your Trusted Real Estate Advisors across Northern California
Whether you’re planning to sell in San Francisco, Marin, Napa, Sonoma, Solano, Yolo, Sacramento, Contra Costa, or Alameda County, our team has local experts ready to help you navigate your next move with confidence and strategy.
EO&A Team
Elizabeth, Anne, Ian, Ksenia, Cliff, Annie, Mike, Nina, Sidra, Karen, Annie, Steven, Gladys, Venus, Najat, and Courtney
707.312.0819 • hello@eoanda.com • www.eoanda.com
DRE# 01388551 • GUIDE Real Estate DRE# 01976964
Real estate and financing information is provided for educational purposes only. Mortgage programs, rates, qualification requirements, seller concessions, and market conditions can change. Buyers should consult their lender and appropriate professional advisors regarding their individual financial situation.
Anne Kennedy
Broker Associate | EO&A | Real Estate in Napa, Sonoma, Solano, Marin, and San Francisco
or another way